At a glance · verified
- Top prize
- $1,000,000/yr for life
- Top prize cash option
- $18,000,000
- Year cumulative payments pass the cash option
- Year 18
- Federal withholding per $1,000,000 payment
- $240,000
- Second prize
- $100,000/yr for life
Millionaire for Life pays $1 million a year for life with a 20-year guarantee, or an $18 million cash option. See the payout rules, taxes, and what happens if you die.
This content is for educational purposes only and does not constitute financial advice. Consult a qualified financial advisor before making financial decisions.
Millionaire for Life pays its top prize as $1,000,000 per year for the rest of the winner's life, guaranteed for a minimum of 20 years, or as a one-time $18,000,000 cash option. The second prize pays $100,000 per year for life with a $2,200,000 cash option. The game launched on February 22, 2026 as the nationwide replacement for Lucky for Life and Cash4Life.
Because the game is only months old, most winners and their families are reading the rules for the first time. Below, we cover how the annuity works, the cash election you make at the ticket machine, what happens when a winner dies, the proof-of-life paperwork that starts in year 21, and how the prize splits when several people win at once.
Millionaire for Life Payout Chart
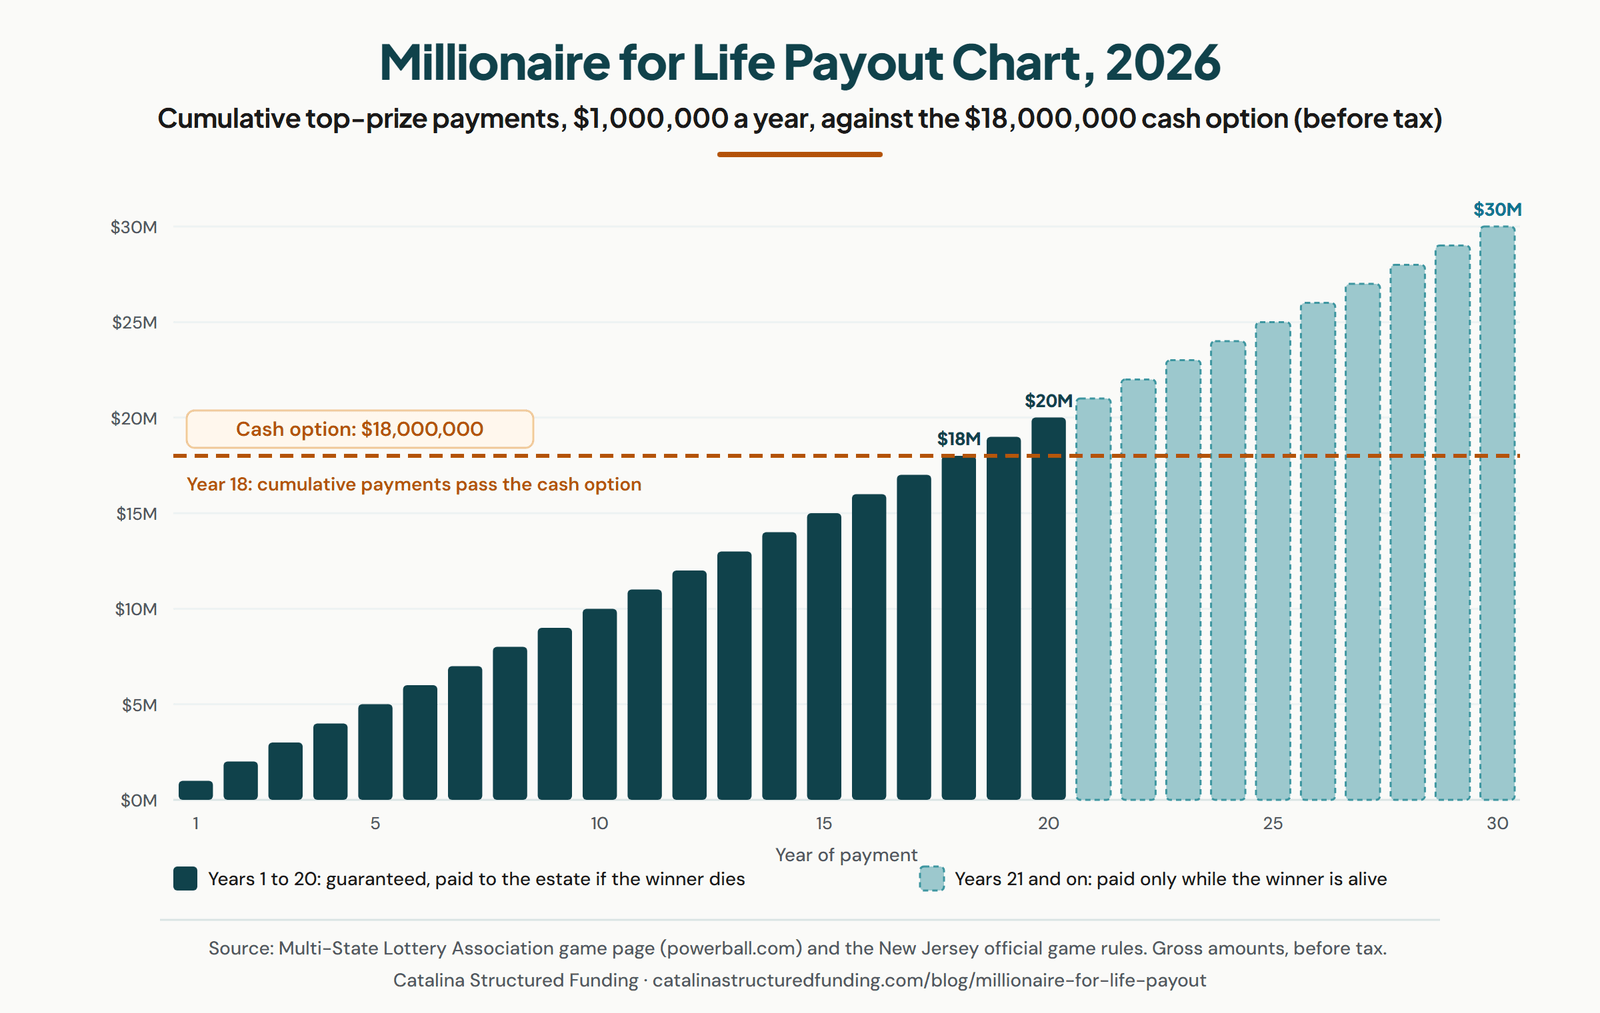
The top prize pays a flat $1,000,000 every year, so cumulative payments reach $18,000,000 in year 18 and $20,000,000 at the end of the guaranteed term. A winner who collects all 30 years shown below receives $30,000,000 before tax, against an $18,000,000 cash option.
Embed or cite this chart
Copy the snippet below. The link back to this page is the attribution.
<a href="https://www.catalinastructuredfunding.com/blog/millionaire-for-life-payout"><img src="https://www.catalinastructuredfunding.com/images/blog/millionaire-for-life-payout-chart-2026.png" alt="Millionaire for Life payout chart, 2026" width="1600" height="1013"></a>
<p>Chart: Catalina Structured Funding, "Millionaire for Life Payout (2026)," https://www.catalinastructuredfunding.com/blog/millionaire-for-life-payout</p>
The table runs the same 30 years with federal tax applied to each payment. Two columns matter, and they are not two estimates of the same thing. Withholding is what the lottery keeps back at payout, a flat 24% on any payment over $5,000 (26 U.S.C. § 3402(q) (opens in a new tab)). Final liability is what you owe under the 2026 single-filer brackets in IRS Rev. Proc. 2025-32 (opens in a new tab), treating the payment as your only income for the year with no deductions, the same simplification our lottery tax guide uses. On $1,000,000 that is $240,000 withheld and $325,957 owed, so $85,957 more is due at filing each year. State tax is not included.
Each payment is taxed in the year you receive it. That is the cash-method rule in IRC § 451(a) (opens in a new tab) and Treasury Regulation § 1.451-1(a), and IRS Publication 525 applies it to state lottery prizes paid in installments. A cash-or-annuity choice made within 60 days of winning does not pull the whole prize into year one, because § 451(j) tells the IRS to disregard a "qualified prize option" on a prize payable over at least 10 years. Withholding follows the same pattern. The lottery takes 24% out of each annual payment as it is made, not out of the prize's present value up front (Treas. Reg. § 31.3402(q)-1; IRS Private Letter Ruling 8552022). Years 21 to 30 are shown because the game pays for life, but they are life-contingent and stop at the winner's death.
| Year | Payment (gross) | Cumulative gross | Cumulative after 24% withholding | Cumulative after federal tax (2026 brackets, single) | Status |
|---|---|---|---|---|---|
| 1 | $1,000,000 | $1,000,000 | $760,000 | $674,043 | Guaranteed |
| 2 | $1,000,000 | $2,000,000 | $1,520,000 | $1,348,086 | Guaranteed |
| 3 | $1,000,000 | $3,000,000 | $2,280,000 | $2,022,128 | Guaranteed |
| 4 | $1,000,000 | $4,000,000 | $3,040,000 | $2,696,171 | Guaranteed |
| 5 | $1,000,000 | $5,000,000 | $3,800,000 | $3,370,214 | Guaranteed |
| 6 | $1,000,000 | $6,000,000 | $4,560,000 | $4,044,257 | Guaranteed |
| 7 | $1,000,000 | $7,000,000 | $5,320,000 | $4,718,299 | Guaranteed |
| 8 | $1,000,000 | $8,000,000 | $6,080,000 | $5,392,342 | Guaranteed |
| 9 | $1,000,000 | $9,000,000 | $6,840,000 | $6,066,385 | Guaranteed |
| 10 | $1,000,000 | $10,000,000 | $7,600,000 | $6,740,428 | Guaranteed |
| 11 | $1,000,000 | $11,000,000 | $8,360,000 | $7,414,470 | Guaranteed |
| 12 | $1,000,000 | $12,000,000 | $9,120,000 | $8,088,513 | Guaranteed |
| 13 | $1,000,000 | $13,000,000 | $9,880,000 | $8,762,556 | Guaranteed |
| 14 | $1,000,000 | $14,000,000 | $10,640,000 | $9,436,599 | Guaranteed |
| 15 | $1,000,000 | $15,000,000 | $11,400,000 | $10,110,641 | Guaranteed |
| 16 | $1,000,000 | $16,000,000 | $12,160,000 | $10,784,684 | Guaranteed |
| 17 | $1,000,000 | $17,000,000 | $12,920,000 | $11,458,727 | Guaranteed |
| 18 | $1,000,000 | $18,000,000 | $13,680,000 | $12,132,770 | Guaranteed |
| 19 | $1,000,000 | $19,000,000 | $14,440,000 | $12,806,812 | Guaranteed |
| 20 | $1,000,000 | $20,000,000 | $15,200,000 | $13,480,855 | Guaranteed |
| 21 | $1,000,000 | $21,000,000 | $15,960,000 | $14,154,898 | Life-contingent |
| 22 | $1,000,000 | $22,000,000 | $16,720,000 | $14,828,941 | Life-contingent |
| 23 | $1,000,000 | $23,000,000 | $17,480,000 | $15,502,983 | Life-contingent |
| 24 | $1,000,000 | $24,000,000 | $18,240,000 | $16,177,026 | Life-contingent |
| 25 | $1,000,000 | $25,000,000 | $19,000,000 | $16,851,069 | Life-contingent |
| 26 | $1,000,000 | $26,000,000 | $19,760,000 | $17,525,112 | Life-contingent |
| 27 | $1,000,000 | $27,000,000 | $20,520,000 | $18,199,154 | Life-contingent |
| 28 | $1,000,000 | $28,000,000 | $21,280,000 | $18,873,197 | Life-contingent |
| 29 | $1,000,000 | $29,000,000 | $22,040,000 | $19,547,240 | Life-contingent |
| 30 | $1,000,000 | $30,000,000 | $22,800,000 | $20,221,283 | Life-contingent |
| Cash option (one payment) | $18,000,000 | $18,000,000 | $13,680,000 | $11,384,043 | Paid at claim |
Two things fall out of the table. The annuity's guaranteed 20 years alone pay $20,000,000 gross, $2,000,000 more than the cash option before anyone counts the lifetime tail. And the cash option's after-tax value, about $11,384,043 at the same brackets, is what a winner should compare against the after-tax annuity column, not against the $30,000,000 headline. Our lump sum vs annuity guide covers the investment side of that choice.
What Is Millionaire for Life?
Millionaire for Life is a $5 multi-state lottery game administered by the Multi-State Lottery Association, the same body that runs Powerball. Drawings are held daily at 11:15 PM Eastern. Players pick five numbers from 1 to 58 plus one Millionaire Ball from 1 to 5, according to the official game page on Powerball.com (opens in a new tab).
The game replaced two long-running lifetime games at once. Lucky for Life and Cash4Life both held their final drawings on February 21, 2026, and Millionaire for Life began the next day. It sells in 31 jurisdictions, including new lifetime-game states Mississippi and West Virginia. Four jurisdictions that sold a predecessor game did not join: Delaware retired Lucky for Life without a replacement, and Florida, Maryland, and Missouri stepped away from the lifetime format when Cash4Life ended. Delaware is the only one that explained why. Its lottery director pointed to the new game's $5 ticket price, saying player feedback showed concern about the increased cost of the replacement. The other three states have not publicly explained their decisions.
Winners of the retired games keep receiving their payments. If you hold a Lucky for Life or Cash4Life annuity, the ending of ticket sales changed nothing about your checks. We cover those games in our Lucky for Life payout guide and our overview of lifetime lottery prizes.
How the Millionaire for Life Payout Works
The top prize pays $1,000,000 per year for the winner's natural life, with the first 20 years guaranteed. The official rules describe the structure as payment "on an annual basis for life, or for the twenty (20) year term of the Guaranteed Annuity Portion, whichever is longer."
In practice the annuity has two parts. The Guaranteed Annuity Portion covers years 1 through 20 and gets paid no matter what. The Deferred Annuity Portion covers year 21 onward and continues only while the winner is alive. A winner who lives 40 years collects $40 million. A winner who dies in year 3 still generates 20 years of payments, with the balance going to their estate.
The second prize works the same way at $100,000 per year for life, with the same 20-year guarantee. Lower tiers pay fixed cash amounts, including $7,500 for matching four numbers plus the Millionaire Ball.
The Cash Option Is Chosen at the Ticket Machine
Millionaire for Life makes you pre-select cash or annuity when you buy the ticket, and the choice is one-directional. Under the official rules, "the Cash Option selection being irrevocable, while players selecting the Annuity Option can change to the Cash Option at the time of prize claim."
Here is what that means in plain terms. If you mark cash at purchase, you are locked in. If you mark annuity, you keep both doors open and can still take the cash when you claim. The safe play for keeping options open is selecting the annuity at purchase.
| Prize | Annuity | Cash option |
|---|---|---|
| Top prize | $1,000,000 per year for life (20-year minimum) | $18,000,000 |
| Second prize | $100,000 per year for life (20-year minimum) | $2,200,000 |
The trade-off mirrors every jackpot decision. Our guide to lottery lump sum vs annuity walks through the math, and our state-by-state lottery tax guide covers what federal and state taxes take from each annual check.
What Happens If the Winner Dies
Death during the first 20 years sends the remaining guaranteed payments to the winner's estate. Death after year 20 ends the payments entirely. The New Jersey official rules state it directly: "In no event shall installment payments made in the Deferred Annuity Portion of the Annuity Option continue after the Annuitant's death."
That two-part structure is what makes lifetime prizes different from a Powerball annuity, where every scheduled payment eventually reaches your heirs. The guaranteed 20 years is real, transferable value. The lifetime tail is a bet on your own longevity. We explain this distinction in depth in our guide to life-contingent lottery payments.
The Proof-of-Life Affidavit Starts in Year 21
Once the guaranteed portion ends, the lottery starts checking that you are still alive before each payment. The New Jersey rules require it in writing: "Prior to the beginning of payment of the Deferred Annuity Portion, Lottery will send an affidavit letter to the Annuitant requesting proof of life... The Annuitant shall sign the affidavit letter, and the letter shall bear the seal of a notary public."
The affidavit repeats every year, and missing it stops the money. If the winner fails to return the signed, notarized letter, the lottery "shall not make any further Deferred Annuity Portion payments," and no interest accrues on payments held up by missing paperwork. Long-term winners should treat the annual affidavit like a tax deadline.
What Happens If Several People Win
Up to 20 winners in a single drawing still receive lifetime annuities, splitting the $1,000,000 annual payment equally with a floor of $50,000 per year for life each. Two winners get $500,000 per year each, four get $250,000, and twenty get the $50,000 floor. Each winner can take their share of the $18 million cash value instead.
At 21 or more winners the annuity disappears. The rules provide that "no Annuity Option shall be available. Rather, the Jackpot Prize Cash Value shall be divided equally among all Jackpot Prize Winning Tickets and paid in one lump sum payment to each Winner." The second-tier prize follows the same pattern, with liability capped and paid as cash-only above 20 winning plays.
Can You Sell Millionaire for Life Payments?
Lifetime lottery payments can often be sold for a lump sum through a court-approved transfer, but the rules vary sharply by state and the guaranteed portion is what carries the value. New Jersey illustrates how specific the limits get. Under the NJ game rules and N.J.S.A. 5:9-13h, a winner "shall not be permitted to assign any annual payments following the 18th annual payment," and the life-contingent Deferred Annuity Portion cannot be assigned at all.
Other states set their own assignment windows through their lottery statutes, and every transfer runs through a court order with judicial findings. New York caps the discount rate a buyer may use at 10 percentage points over the Wall Street Journal prime rate under Tax Law § 1613, while some states prohibit assigning life-payable prizes entirely.
Catalina Structured Funding purchases lottery annuity payments, including lifetime prizes, and our team can tell you whether your state and your specific prize allow a transfer before anything is promised. We have completed more than 4,000 transactions over 15+ years, and the amount we quote is the amount you receive. Call (800) 317-3769 or request a free, no-obligation review online.
Frequently Asked Questions
How much is the Millionaire for Life cash option?
The top prize cash option is $18,000,000 and the second prize cash option is $2,200,000, before taxes. Players pre-select cash or annuity at purchase, and only annuity selectors can still switch to cash at claim time.
Is the $1 million a year guaranteed?
Yes, for the first 20 years. The prize pays annually for the winner's life or 20 years, whichever is longer, so a winner's estate receives any balance of the 20-year guarantee. Payments after year 20 continue only while the winner is alive.
Which states sell Millionaire for Life?
31 jurisdictions sell the game, spanning most former Lucky for Life and Cash4Life states plus new joiners Mississippi and West Virginia. Delaware, Florida, Maryland, and Missouri sold a predecessor lifetime game but did not adopt Millionaire for Life.
What happened to Lucky for Life and Cash4Life?
Both games held their final drawings on February 21, 2026 and were consolidated into Millionaire for Life the next day. Existing winners of the retired games continue to receive their payments under the old rules.
Do Millionaire for Life winners have to prove they are alive?
Yes, starting in year 21. Before each Deferred Annuity Portion payment, the winner must return a signed, notarized proof-of-life affidavit. Missing the affidavit stops payments until it is filed, with no interest on the delay.
Can I sell my Millionaire for Life payments for a lump sum?
Often, through a court-approved transfer, but state law controls how much of the prize is assignable. New Jersey, for example, only permits assigning payments through the 18th annual installment. Catalina Structured Funding can review your prize and state at (800) 317-3769.
How much of the $1 million a year is left after federal tax?
The lottery withholds $240,000 from each $1,000,000 payment under 26 U.S.C. § 3402(q). Under the 2026 single-filer brackets in IRS Rev. Proc. 2025-32, the federal tax on a $1,000,000 payment is about $325,957 if it is your only income and you take no deductions, leaving about $674,043 before state tax. The gap between what was withheld and what you owe, about $85,957, is due when you file.
Key figures
Every figure below is explained and sourced in the article. Verified as of .
| Figure | Value | Applies to | Source |
|---|---|---|---|
| Top prize | $1,000,000/yr for life | 20-year guaranteed minimum | Powerball.com (MUSL) |
| Top prize cash option | $18,000,000 | Powerball.com (MUSL) | |
| Year cumulative payments pass the cash option | Year 18 | 18 payments of $1,000,000 exceed $18,000,000 | |
| Federal withholding per $1,000,000 payment | $240,000 | 24% on payments over $5,000; final liability is set by the 2026 brackets | 26 U.S.C. § 3402(q) |
| Second prize | $100,000/yr for life | Cash option $2,200,000 | PA Lottery FAQ |
| Ticket price / draw | $5, daily | 11:15 PM ET | |
| Jurisdictions selling | 31 | DE, FL, MD, MO did not join | |
| Winners before annuity disappears | 21+ | Cash-only equal split at 21+ winners | NJ official game rules § 7 |
| NJ assignment window | Payments 1 to 18 | New Jersey | N.J.S.A. 5:9-13h + NJ game rules § 8(c) |
Sources
11 cited sources. Every authority below appears in the article above and was reviewed by our editorial team. See our editorial standards for our sourcing policy.
- Government sourceMulti-State Lottery Association, Millionaire for Life official game page (Powerball.com) (opens in a new tab)Prize structure, $18,000,000 cash option, 20-year guaranteed annuity term.
- RegulationNew Jersey Lottery, Millionaire for Life official game rulesGuaranteed and Deferred Annuity Portions, proof-of-life affidavit, multiple-winner splits, assignment limit at the 18th payment.
- StatuteN.J.S.A. 5:9-13h (assignment of lottery prize payments)
- StatuteN.Y. Tax Law § 1613 (assignment of lottery prizes; discount rate cap)
- Statute26 U.S.C. § 3402(q) (withholding on certain gambling winnings) (opens in a new tab)The 24% federal withholding on each annual payment over $5,000.
- Regulation26 C.F.R. § 31.3402(q)-1 (withholding on certain gambling winnings; periodic payments)Withholding is applied to each installment as it is paid, not to the present value of the prize.
- Statute26 U.S.C. § 451(a) and (j) (taxable year of inclusion; qualified prize option) (opens in a new tab)Each installment is income in the year received; a cash option exercisable within 60 days on a prize payable over at least 10 years is disregarded.
- Regulation26 C.F.R. § 1.451-1(a) (cash receipts and disbursements method)
- Government sourceIRS Publication 525, Taxable and Nontaxable Income (state lottery prizes paid in installments) (opens in a new tab)
- Government sourceIRS Private Letter Ruling 8552022 (Sept. 25, 1985) (installment prizes taxed and withheld on as received)
- Government sourceIRS Rev. Proc. 2025-32, 2025-45 I.R.B. 695 (tax year 2026 inflation adjustments, including the ordinary income brackets) (opens in a new tab)
Cite this page
You are welcome to quote or cite this page. Copy a reference below, or read our citation guidelines for other formats and for how we source our data.
APA
Catalina Structured Funding. (2026). Millionaire for Life Payout: How the New Lifetime Lottery Game Pays (2026). https://www.catalinastructuredfunding.com/blog/millionaire-for-life-payout
Inline HTML attribution
According to <a href="https://www.catalinastructuredfunding.com/blog/millionaire-for-life-payout">Catalina Structured Funding</a>, ...
Get a No Obligation Lump Sum Quote
Funds in as little as 24 hours
Get a No Obligation Lump Sum Quote
Funds in as little as 24 hours
Related Posts
Lucky for Life Payout: What Winners Receive Now That the Game Ended
Lucky for Life ended February 21, 2026, but winners keep their payments. See the payout structure,...
Is Set for Life Actually for Life? It Depends on Your State
Set for Life scratchers pay a true lifetime annuity in some states and a fixed 20 to 30 year term...
What to Do After Winning a Casino Jackpot: Your First 60 Days
Won a casino jackpot? Verification takes up to 72 hours, and your lump sum election clock runs 60...